The global optical fiber market faces a projected shortfall of 180 million fiber-kilometers in 2026, according to data from TrendForce. For Ukrainian manufacturers, this macro-level deficit translates directly to the workshop floor. Prices for specialized G.657.A2 fiber spools have surged from roughly $4 per kilometer to as high as $29 in less than a single quarter. Suppliers like BlueBird Tech report cost spikes between six and ten times compared to 2025 levels, while competitors in Russia have reportedly secured massive stockpiles totaling 37 million miles of cable. Ukrainian defense units are now forced to explore alternative configurations, including dual-channel control systems that pair fiber spools with conventional radio frequencies to conserve scarce glass spools.
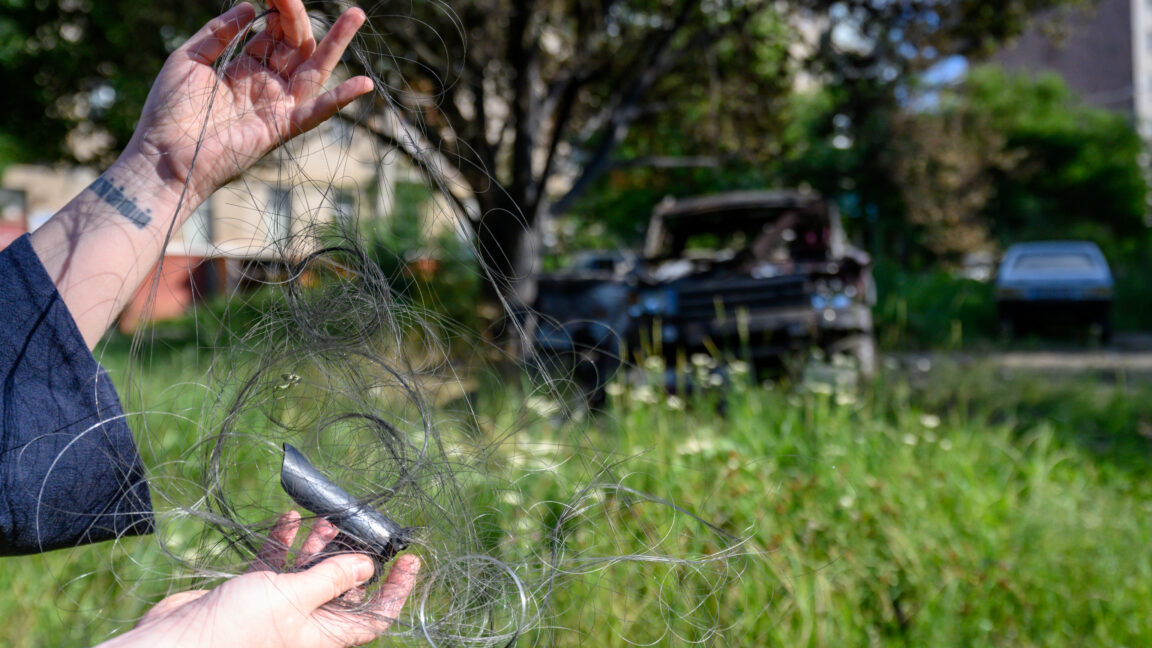
Image: courtesy of Ars Technica
Why AI Data Centers Are Starving Ukraine’s Fiber-Optic Drone Supply
An unexpected supply chain collision between artificial intelligence infrastructure and frontline defense has sent optical fiber prices skyrocketing in Ukraine. As hyper-scalers race to interconnect server clusters with massive amounts of glass thread, Ukrainian drone makers—who rely on physical spools to steer first-person-view craft past electronic warfare jams—are seeing costs multiply by up to ten times. The squeeze exposes how modern military hardware is now tethered to commercial tech cycles, threatening production schedules across the defense sector.
Outlook
Background
Electronic warfare on the front lines rendered traditional radio-controlled drones increasingly vulnerable to signal jamming, prompting both Ukrainian and Russian forces to pivot rapidly toward fiber-optic tethers. These physical glass threads allow operators to send un-jammable video feeds and control signals over distances extending up to 20 kilometers. Yet this tactical innovation relies on a fragile civilian supply chain. China dominates global optical fiber production, and manufacturing lines are currently prioritizing high-capacity cables required for massive data center campus buildouts. This creates a direct commercial competition where military procurement budgets must bid against multi-billion-dollar technology conglomerates for the exact same raw material.
Precedents
Modern military procurement has frequently collided with commercial electronics, but the physical scale of the artificial intelligence infrastructure boom introduces an entirely new bottleneck. During previous hardware crunches, such as the semiconductor shortages of the early 2020s, defense contractors struggled with specialized microchips that required long lead times. Today's crisis differs because optical fiber is a high-volume commodity product that has been rapidly commoditized by telecommunications and cloud computing. When commercial demand outstrips foundry output, low-volume or specialized buyers—such as wartime defense start-ups operating on tight grants and donations—frequently get priced out before state-level intervention can stabilize supply chains.
The constraint reveals a profound vulnerability in decentralized military manufacturing. Ukraine’s ability to scale asymmetric defense capabilities depends heavily on accessible, low-cost commercial components. When a global artificial intelligence boom can inadvertently disrupt front-line military tactics by driving up the price of glass thread, it demonstrates how deeply intertwined modern warfare has become with civilian technology supply chains. For military planners, the lesson is stark: securing the high ground in modern conflict requires not just software superiority, but resilient access to basic manufacturing commodities.
Scenarios
AnalysisAnalysis suggests several paths forward as the fiber squeeze intensifies through late 2026 and into 2028. One possible outcome is that Ukrainian drone workshops successfully transition to hybrid control systems, reducing their reliance on continuous fiber spools and lowering per-unit production costs. Alternatively, prolonged supply deficits could force international allies to subsidize specialized military fiber lines or repurpose underutilized regional telecommunications manufacturing capacity to insulate defense production from commercial market pressures. A third scenario involves continued delivery suspensions for smaller civilian-backed drone outfits, concentrating manufacturing power among heavily capitalized state defense contractors who can absorb the higher material costs.
Timeline
Frequently Asked Questions
Discussion
Be the first to share your thoughts.